Insights
Multifamily Real Estate Investing: A Practical Guide
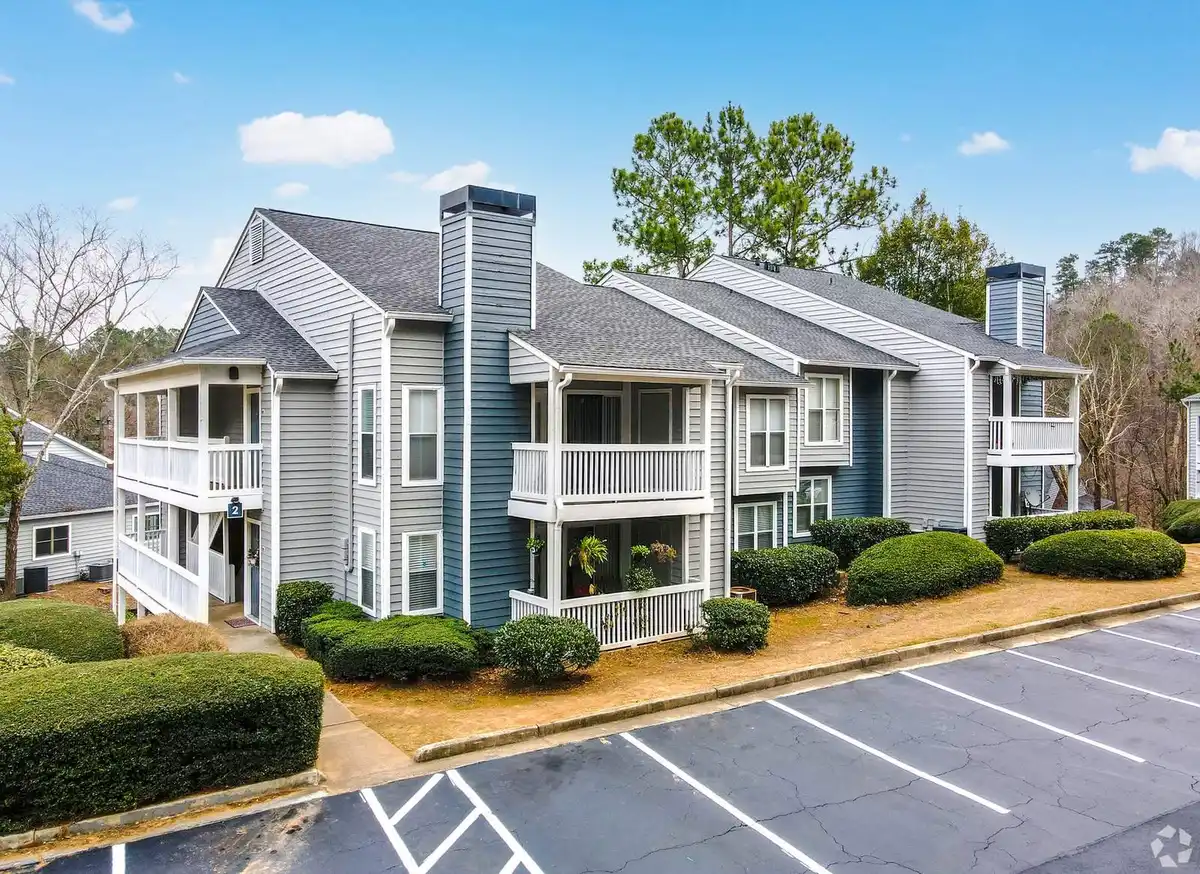
| What it is | Owning apartment housing with more than one unit, either in your own name or through a sponsor, a fund or a REIT. |
|---|---|
| Four ways in | Buy a property yourself, own a limited-partner interest, buy a public REIT, or buy a non-traded REIT or private fund. |
| Who can invest privately | Rule 506(c) offerings are limited to accredited investors, and the sponsor must take reasonable steps to verify that status. |
| Main risks | You can lose capital. The interest can be illiquid, and debt can magnify a bad year. |
| Tax form by path | Schedule E for property you own, Schedule K-1 (Form 1065) for many partnerships, and Form 1099-DIV for many REIT dividends. |
| Where to go next | How a real estate syndication works. |
Multifamily real estate investing means putting capital into apartment housing, either by buying a building yourself or by owning a share through a private sponsor, a public REIT or a fund. Each path trades control for convenience differently. This guide compares the four paths, the property classes, the numbers that matter and the risks before you read any offering.
What is multifamily real estate investing?
Multifamily real estate investing is the ownership of apartment housing that has more than one unit, held for rent rather than as your own home. The rent from several leases is what pays expenses, the loan and, if anything is left, the owner.
People use the shorter phrase multifamily investing for the same idea. The building can be a small property you buy in your own name, or a larger community owned by a partnership or a REIT. The label describes the housing, not a promise about income.
A useful first split is who signs, who manages and who can sell. Those three answers change the tax form, the fees and how long your money stays put. The next section puts the four common paths side by side.
What are the four ways to invest in multifamily?
The four common ways to invest in multifamily housing are direct ownership, a private limited-partner interest, a public REIT and a non-traded REIT or private fund. They are not four versions of the same investment. They differ in who borrows, who can be forced to send more cash, and how you get out.
| Direct ownership | Private syndication (LP interest) | Public REIT | Non-traded REIT or private fund | |
|---|---|---|---|---|
| Who runs the property | You, or a manager you hire | The sponsor and its property manager | The REIT's management | The sponsor or advisor |
| Who signs the loan | You | The borrowing company the sponsor controls | The REIT | The fund or REIT, not you personally |
| Control over decisions | You approve sales, loans and major repairs | The operating agreement limits investor votes | Shareholders do not run buildings | Usually limited, and stated in the offering |
| Liquidity | You can list the property, but a sale takes time | Often restricted for years, with transfer limits | Shares trade on an exchange | Often limited. Investor.gov warns that non-traded REITs are illiquid |
| Who can invest | Anyone who can qualify for the loan | Accredited investors when the offering uses Rule 506(c) | Anyone a brokerage will accept | Varies. Read the offering for the test |
| Typical tax form | Schedule E | Schedule K-1 (Form 1065) | Form 1099-DIV | Form 1099-DIV or a Schedule K-1 |
| Fees to look for | Loan costs, repairs and management | Acquisition, asset-management and disposition fees | The REIT's expense ratio and any load | Up-front fees. Investor.gov notes non-traded REITs often charge about 9 to 10 percent up front |
Direct ownership means the deed and the loan are yours. You choose the manager, you approve a sale, and the rent and expenses land on your own tax return, usually on Schedule E. You also absorb a vacant unit, a roof and a lender who wants to be paid on the first of the month.
A private syndication is a limited-partner interest in a partnership that owns one property or a small group of them. Rule 506(b) of Regulation D does not allow general solicitation, and it can include up to 35 sophisticated non-accredited purchasers along with accredited investors. Rule 506(c) allows general solicitation only if every purchaser is accredited and the issuer takes reasonable steps to verify that.
Investor.gov explains that a REIT sells shares and must distribute most of its taxable income as dividends, which are generally taxed as ordinary income. A public REIT trades on an exchange. A non-traded REIT is illiquid, often charges about 9 to 10 percent in up-front fees, and can pay distributions from offering proceeds rather than from rent.
A private fund can look like a syndication spread across more than one property. Read who can invest, what the fund can buy, and when you are allowed to leave. The securities in a Regulation D offering are restricted, and a Form D is filed after the first sale and can be searched on EDGAR.
The rule text is summarized on the Investor.gov Rule 506 page, and the accredited-investor tests are in 17 CFR 230.501. REIT fees and liquidity are described on the Investor.gov REIT page.
What do Class A, B and C apartments mean?
Class A, Class B and Class C are industry labels for the age, condition and rent level of an apartment property, and they are not defined in a statute. Brokers and sponsors use them as shorthand. Two buildings with the same letter can still sit in very different neighborhoods.
| Class A | Class B | Class C | |
|---|---|---|---|
| Typical age and condition | Newer or recently renovated | Older but maintained | Older, with deferred repairs |
| Rent level versus the local market | Top of the local range | Near the middle of the local range | Below the local range |
| Typical business plan | Stabilized hold | Value-add renovations | Heavy repositioning |
| Operating intensity | Lower day-to-day repair load | A steady renovation and leasing plan | High repair and turnover load |
| Main risk | Paying a high price if rents stall | Renovations that cost more or lease up slower | Repairs, vacancy and a tenant base that cannot absorb higher rent |
Class A is the newer or newly renovated end of a market, with rents near the top of what local tenants pay. The business plan is often to keep the property full and well kept. The risk is paying a price that only works if those rents hold.
Class B is the middle of the market. A value-add plan renovates kitchens, common areas or exteriors and then asks for a higher rent. The risk is that the work costs more, or leases up slower, than the model assumed.
Class C is older housing, often with lower rents and more repairs. A heavy repositioning plan can change who the property serves. The risk is vacancy and a repair bill that the current rent cannot cover.
Ask which letter the sponsor is using, and what would have to be true for the building to deserve the next letter. The photos and the trailing twelve months of expenses answer that question better than the brochure.
How do multifamily investments make money, and lose it?
A multifamily investment makes money from rent, and it can also make money if the property is refinanced or sold for more than the debt and the costs. It loses money when vacancy, repairs or the loan consume that rent, or when a sale does not cover what is owed.
Net operating income, or NOI, is income from the property minus operating expenses, before the loan payment and before income tax. A cap rate is NOI divided by the price, and it is a way to compare prices, not a forecast of what you will be paid. The debt service coverage ratio, or DSCR, asks whether NOI covers the loan payment. A ratio under 1 means the property's operations do not cover the debt.
Leverage is the loan. It can raise the result for the equity when NOI grows, and it can erase equity when NOI falls or the rate resets. A vacancy is not a small annoyance in a thin model. Empty apartments still owe taxes, insurance and the lender.
A refinance can return cash if a new loan is larger than the old one, and it can also raise the payment. A sale is the end of that property's plan, and the cash left after the loan and the costs follows the operating agreement. Neither event is guaranteed, and neither one is the same number as taxable income. The tax lines are covered in how to read a real estate K-1.
If a term in an offering is still unclear, the team can point you to the paragraph that defines it.
Talk to the teamCall (301) 900-2625What risks should a beginner understand first?
The first risks in multifamily investing are loss of capital, illiquidity, leverage, concentration and sponsor risk. Each one can show up even when the building looks full on a tour.
Loss of capital means the cash you put in is not insured, and a sale or a foreclosure can return less than you invested, including zero. Illiquidity means you may not be able to sell a private interest when you want the money. A public REIT is the path that usually lets you sell on an exchange. The other three paths can take months or years.
Leverage magnifies both directions. Concentration means one property, one city or one sponsor can dominate the result. Sponsor risk is the chance that the people who run the property report late, overpay, or cannot execute the repairs they described.
A beginner should be able to point to each of those five risks in the document, in one sentence each. If the offering describes only the upside, the missing half is the part that matters in a bad year. Questions to press on are listed in questions to ask a sponsor before investing.
Who is multifamily investing a fit for?
Multifamily investing is a fit for someone who can leave capital invested for the hold the documents describe, and who does not need that capital for living expenses. It is a poor fit for money that has a near-term bill attached.
W-2 professionals often look at a private offering because they do not want a second job as a landlord. The passive-activity rules still decide whether a paper loss can offset wages, and those rules are explained in the K-1 guide, not assumed here. A one-sentence version: most limited partners cannot use a rental loss against W-2 wages unless a specific IRS test is met.
Guides written for particular readers live on real estate investing for doctors, real estate investing for nurses, real estate investing for business owners and U.S. multifamily for international investors. Retirement-account money has its own rules on self-directed IRA real estate.
A fit is about time horizon and risk, not about how many other people have already joined a sponsor.
How do you evaluate a multifamily deal before investing?
You evaluate a multifamily deal by reading the property, the loan, the fees and the sponsor before you read the projected return. The order matters because a high projection cannot repair a thin loan or a missing track record.
- Read the trailing twelve months of income and expenses, not only the pro forma.
- Find the loan: maturity, rate, interest-only period and what happens at a reset.
- List every fee: acquisition, asset management, property management and disposition.
- Find the preferred return, the split and whether an unpaid amount carries forward. The mechanics are in preferred returns in real estate.
- Ask who operates the property and who signs the loan.
- Read how distributions are paused, using how real estate syndication distributions work.
- Check the sponsor's past deals, including ones that missed the plan, and the firm's underwriting approach.
Then read the risks section of the offering as if it were the only page. If you still want the investment, you at least know which sentences you are accepting.
Where XSITE fits, and what it is not
This guide compares ways to own apartment housing. It does not sell a building, and it does not choose a path for you.
XSITE Capital is one sponsor among the private-syndication path described above. What the firm will and will not do is on how a real estate syndication works, and the communities themselves are on the portfolio.
Eligibility, including who may buy a private offering, is answered on the FAQ. A partnership interest is not a REIT share and not a savings account.
Targeted returns are estimates, not guarantees. Past performance does not guarantee future results. Investing involves risk, including loss of principal. Offerings are available to accredited investors only. General education, not tax, legal or investment advice. Tax rules change.
Related reading
Questions
Questions about multifamily investing
How is multifamily investing different from owning a rental house?
What is a good cap rate for an apartment building?
Do I need to be an accredited investor to invest in multifamily?
What is NOI in multifamily real estate?
Is a REIT or a private syndication better for apartment exposure?
Can I invest in multifamily from out of state?
A private conversation
Speak with our team
Twenty minutes with the team. No obligation to invest.
Honesty · Integrity · Abundance · Humility · Tenacity