U.S. investor path
- Rule 506(c), if applicable
- Accreditation verification
- Domestic funding
- U.S. tax documents
INTERNATIONAL INVESTORS
Learn how eligible international investors may access U.S. multifamily offerings, including subscription, identity verification, funding, reporting and cross-border tax considerations.
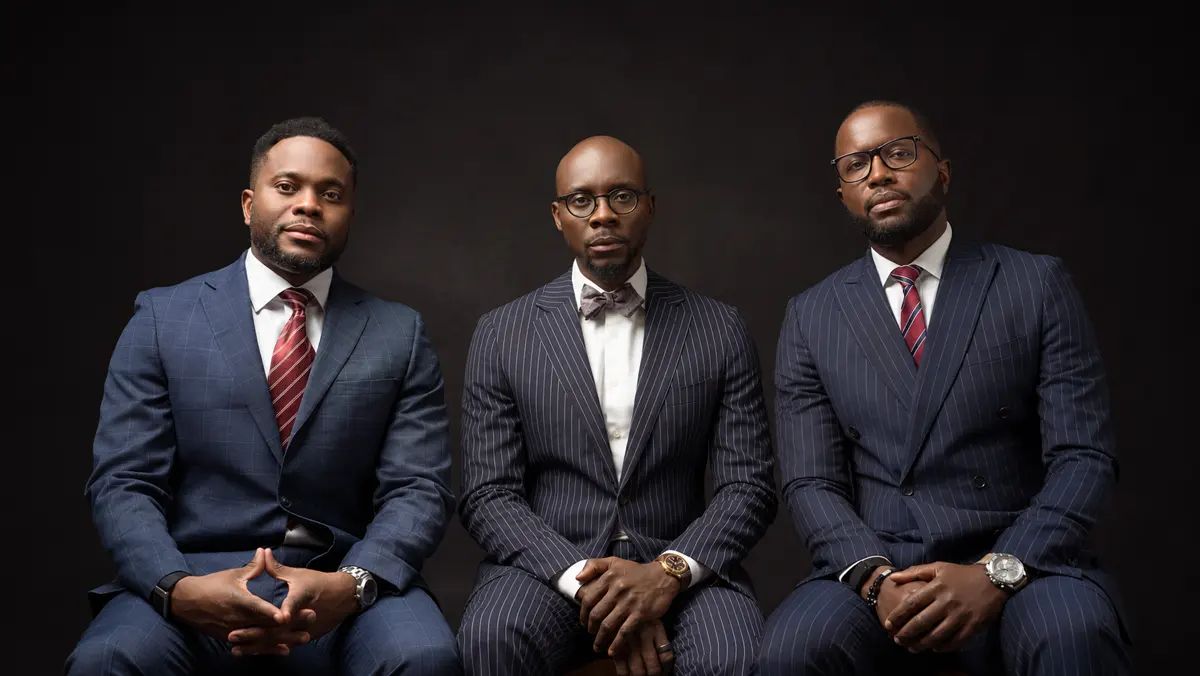
Dr. Julius Oni, Leslie Awasom, and Tenny Tolofari co-founded XSITE Capital after immigrating to the United States. Dr. Oni is an orthopedic surgeon and the firm’s chief executive. Leslie Awasom is chief operating officer. Tenny Tolofari, who came to America from Nigeria, leads acquisitions.
That history is why investors outside the United States have a page of their own. The sections below explain how an eligible investor reviews a subscription. They are not a recommendation.
A person outside the United States may be able to invest when that offering’s documents and applicable law allow it. A job title, a visa, or a country of residence does not by itself decide eligibility.
For many U.S. private offerings, accredited-investor status is established through income, net worth, or certain professional credentials. Income qualification generally means exceeding the threshold in each of the prior two years, with a reasonable expectation for the current year. The SEC’s accredited investor page states the tests. An international path may also require a non-U.S.-person certification, or another certification that offering specifies.
Recent offerings have generally started at $100,000. Minimums vary by offering. The offering documents state the figure.
The portfolio page reports $276 million of portfolio value and 1,422 apartments currently under management. Portfolio value is the aggregate purchase price plus capital improvements of properties currently under management.
This diagram is illustrative of typical paths. It is not a photograph, and it is not a recommendation. The exact structure, including whether Rule 506(c) or Regulation S applies, is the one stated in that offering’s documents.
Underlying investment
The appropriate subscription path depends on the investor’s legal, tax and securities-law status—not only physical residence. XSITE and the investor’s advisors must confirm the appropriate path.
Eligibility can depend on non-U.S.-person status, whether the transaction occurs offshore, local solicitation rules, and other offering conditions. Regulation S does not simply mean “foreign investor.”
Where an offering uses more than one vehicle, those vehicles can differ in legal entities, tax treatment, withholding, subscription documents, transfer restrictions, reporting documents, and fees or administrative expenses. Where the documents say so, a parallel vehicle is intended to invest in the same underlying opportunity.
A subscription is completed in the way that offering describes, often electronically. Before funding, expect identity verification, anti-money-laundering review, and source-of-funds questions.
XSITE can provide the offering materials. The investor and the investor’s advisors review them. XSITE does not give legal or tax advice on those documents.
International wires are a typical way to send a subscription. A U.S. bank account is not stated here as a requirement. The offering’s funding instructions control, and the investor’s bank may charge currency-conversion costs and wire fees.
Subscription amounts in XSITE offering materials are stated in U.S. dollars. Conversion from another currency, if any, is handled by the banks involved.
International investors may have U.S. filing, identification and withholding obligations, including obligations that arise without a matching cash distribution. Requirements vary by investor type, country, treaty status and offering structure. Prospective investors should obtain independent U.S. and home-country tax advice before subscribing. Consult your tax professional.
Foreign partners may face withholding on effectively connected taxable income even when there is no matching cash distribution. The IRS notes that partnership withholding can apply regardless of distributions. Form W-8BEN is generally for foreign individuals, while foreign entities may need different documentation such as Form W-8BEN-E. Those are examples, not a complete list. See the IRS notes on partnerships with foreign partners and on forms for foreign beneficial owners.
Reporting may include a Schedule K-1 and/or other withholding statements, as the offering provides. This page does not promise that every international structure issues a K-1.
Home-country securities laws and tax laws may apply in addition to U.S. rules. An investor’s own advisors apply those rules to the person and the offering.
XSITE can provide offering materials for that review. XSITE does not interpret home-country law.
A private real estate interest is generally illiquid. Transfer can be restricted by the offering documents and by law. You may not be able to sell when you want, and value can fall. Debt, occupancy, and operations all matter.
Cross-border investors may also have estate-tax questions. This page does not give personal estate-tax advice. Nothing here is a guaranteed return.
This page does not publish a list of countries XSITE can or cannot accept. Eligibility and accepted jurisdictions are confirmed during subscription, against that offering’s documents and applicable law. Some countries or investor types may not be accepted.
A foreign company or a trust is not approved or refused here. Whether that investor type can subscribe depends on the offering and must be confirmed. Materials can be provided for the investor’s advisors.
Read the process on this page, then ask the team for the offering materials your advisors should review.
These notes are for information only. They are not an offer to sell, or a solicitation of an offer to buy, any security. Past performance does not predict future returns, and an investment can lose money. Nothing on this page is investment, legal, or tax advice. The offering documents govern.